GST Appeal Pre-Deposit: How Much to Pay
Before an APL-01 appeal can be filed, Section 107(6) requires the admitted amount in full and 10% of the disputed tax. This guide explains the cap, the DRC-03 and electronic credit ledger routes, and the 2025-26 rulings that matter to taxpayers in West Bengal.
What the pre-deposit is and why an appeal fails without it
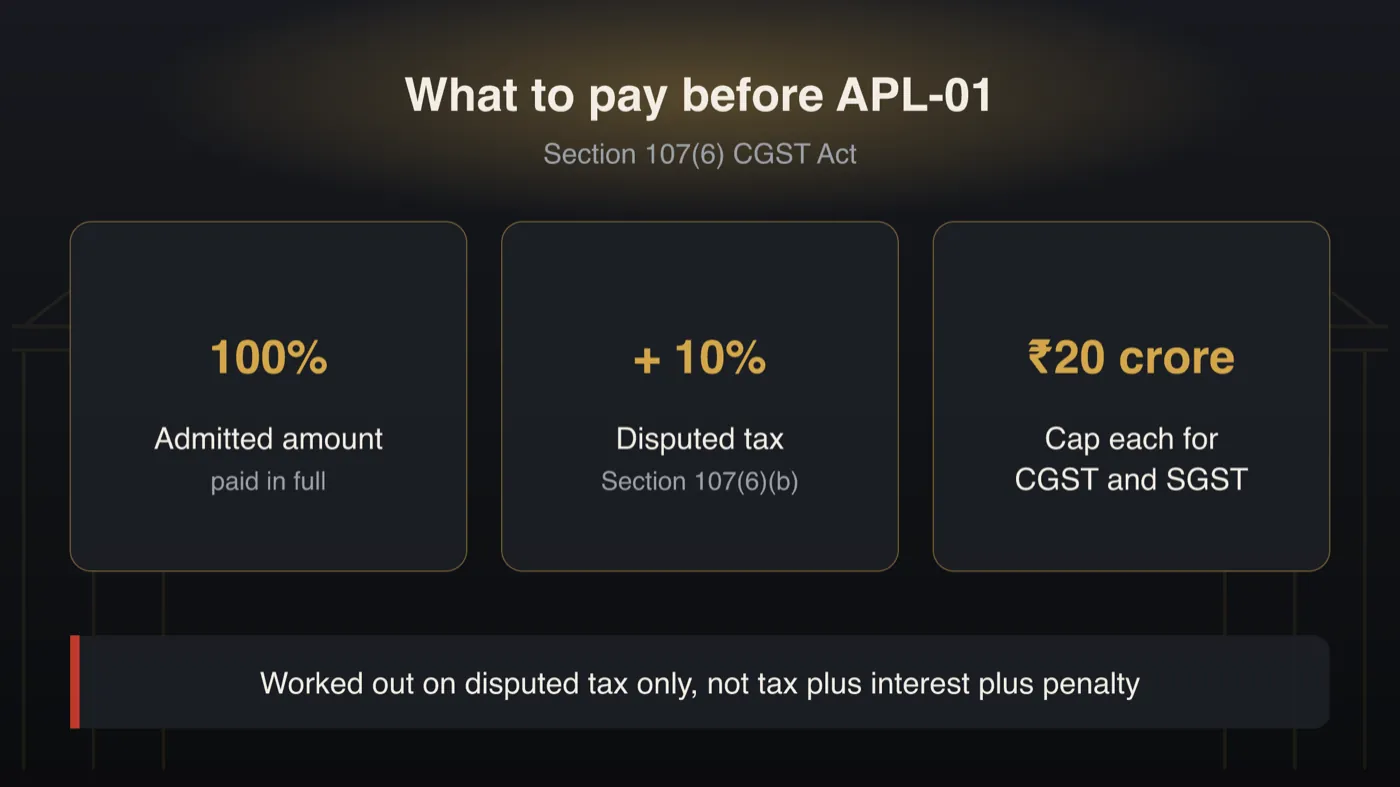
A first appeal against a GST order is filed online in Form APL-01, and the portal will not accept it until the pre-deposit under Section 107(6) of the CGST Act, 2017 has been paid. The West Bengal GST Act carries the same provision. The appellant must pay the whole of the tax, interest, fine, fee and penalty that is admitted, and 10% of the tax still in dispute, subject to a cap of ₹20 crore each for CGST and SGST. Missing this step is among the commonest reasons a genuine appeal never reaches a hearing.
The amount is worked out separately for CGST and SGST, and it is calculated on the disputed tax only, not on tax plus interest plus penalty. Once it is paid, recovery of the balance demand is deemed stayed under Section 107(7). If you have received a demand order and the clock is running, read our note on what to do after a GST demand notice, or speak to a GST lawyer in Kolkata about the figures for your order. Please confirm every amount against the order and the current statute before paying.
The periods that matter for a GST appeal
These are the main statutory periods, counted from the date the order is communicated.
Short explainers from Adv. Sudip Patra
More short explainers on our YouTube channel: Patra’s Law Chambers on YouTube ↗
Which GST paper or situation are you in?
Pick the one that matches your case to see the usual forum and step. This is general information, not advice on your file, and the details change with the facts and dates.
Choose one of the options above.
From the GST order to a stay on recovery
This is the usual path for a taxpayer in West Bengal appealing a demand order. Your dates and forum depend on who passed the order.
Note the date the order was uploaded on the portal. Also check the Additional Notices and Orders tab, because orders sometimes sit there unnoticed.
Add up the admitted amount and 10% of the disputed tax, separately for CGST and SGST. The GST lawyer page explains how the firm handles GST notices and orders.
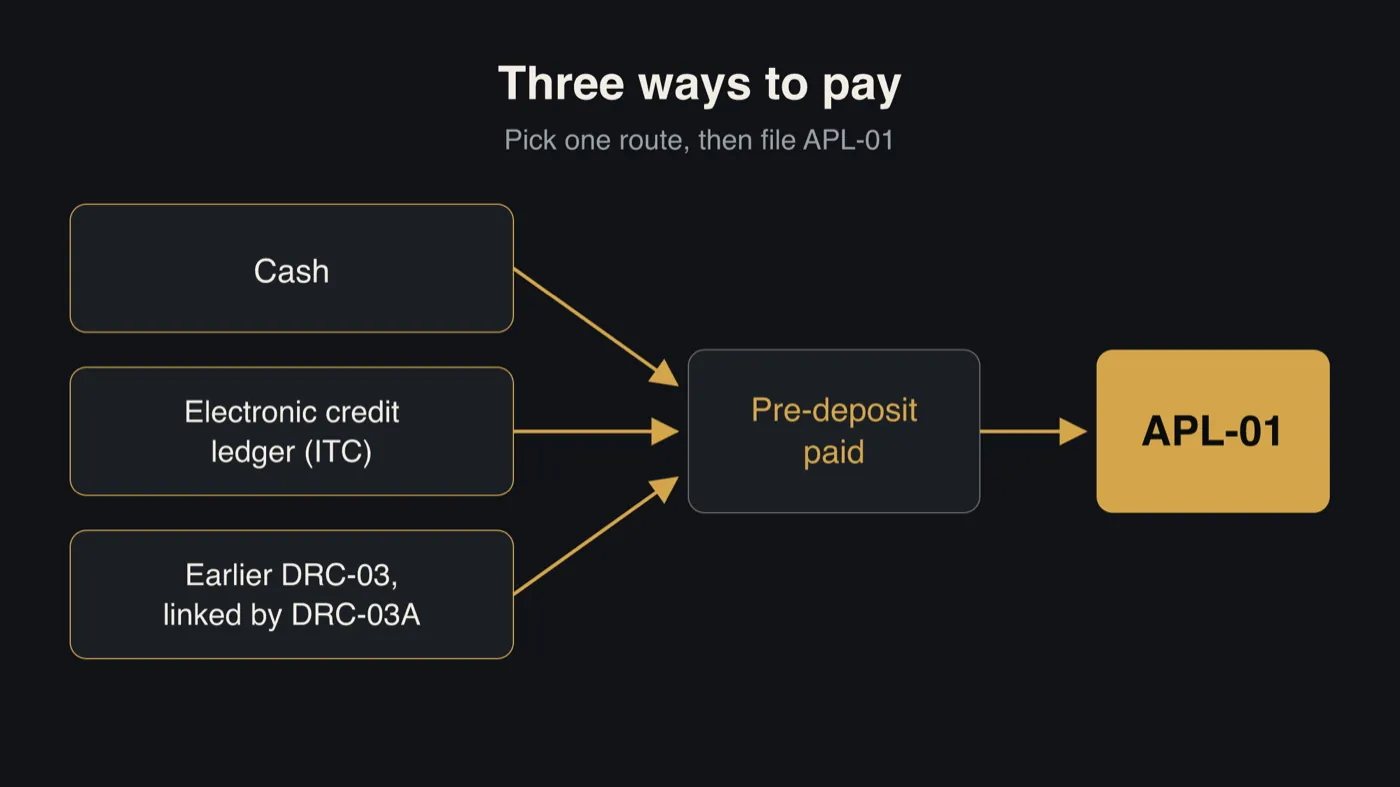
Pay from the cash or credit ledger, or link an earlier DRC-03 through DRC-03A, then file APL-01 on gst.gov.in. The final acknowledgement is APL-02.
Section 107(4) allows one more month for sufficient cause. In Calcutta, S.K. Chakraborty & Sons (2023) holds that section 5 of the Limitation Act can apply beyond that, but do not plan around it.
Under section 107(7) the balance demand is stayed. If the department still recovers, a writ petition in the Calcutta High Court may be considered.
A further 10% of the disputed tax is payable under section 112(8), so about 20% in all. Verify the current GSTAT time limits and bench details before filing.
Three things people get wrong. Tap a card
No. The 10% is calculated on the disputed tax only, and the Calcutta High Court has said so. Interest and penalty are not added where tax is also in dispute.
Not necessarily. CBIC’s 2022 instruction and the Bombay and Gujarat High Courts allow the Electronic Credit Ledger. The Supreme Court dismissed the Revenue’s SLP in Yasho Industries in May 2025, but verify the position for your case.
Usually not. Courts send the party to the statutory appeal. Writs succeed mainly for natural justice failures or orders passed without jurisdiction, as in other Calcutta High Court matters.
Where pre-deposit questions arise
How much to pay
The admitted amount in full, plus 10% of the disputed tax, capped at ₹20 crore each for CGST and SGST. Interest and penalty are not added to the 10% where tax is also disputed. Penalty-only orders passed in proceedings begun on or after 1 October 2025 need 10% of the penalty.
Credit ledger, cash or an old DRC-03
Courts including the Bombay and Gujarat High Courts have accepted payment from the electronic credit ledger, and the Supreme Court dismissed the Revenue’s SLP in the Gujarat case in May 2025. An earlier DRC-03 payment can be linked to the demand through DRC-03A under Rule 142(2B).
Delay, recovery and writs
The Calcutta High Court has held that Section 5 of the Limitation Act can apply to Section 107 appeals, and has criticised recovery after a pre-deposit. A writ is usually refused for avoiding the deposit; see our guide to a writ petition in the Calcutta High Court.
The second appeal
A further appeal to the GST Appellate Tribunal requires another 10% of the remaining disputed tax under Section 112(8), so about 20% in all. Questions of law beyond that may reach the Supreme Court by special leave petition under Article 136.
Before you file APL-01
- Confirm the date the order was communicated, including the Additional Notices and Orders tab
- Split the admitted and disputed tax for CGST and SGST
- Decide the payment route: cash, credit ledger, or DRC-03 linked by DRC-03A
- Check whether the proceedings began before or after 1 October 2025 for penalty-only orders
- Keep the order, notice, reply, ledger statements and payment proof together
- Customs and import-export demands follow a different appeal route; see our customs lawyer page
The rulings that decide how and when the GST appeal pre-deposit is paid
High Courts have settled the main questions on the Section 107(6) pre-deposit: whether it can come from input tax credit, whether the 2025 penalty rule applies to old cases, and what happens when the appeal is late. Check every ruling below against the full judgment before relying on it in your own matter.
2024
Pre-deposit may be paid from ITC
The Gujarat High Court held that the words “has paid” in Section 107(6)(b) of the CGST Act are not limited to cash. A pre-deposit debited from the Electronic Credit Ledger is valid, which matches the CBIC instruction of 6 July 2022. The Supreme Court dismissed the Revenue’s SLP without giving reasons, so the High Court ruling stands.
2022
10% can come from the credit ledger
The Bombay High Court allowed the 10% of disputed tax to be paid from either the electronic cash ledger or the electronic credit ledger, relying on Section 49(4) and the CBIC clarification. In 2025 the same court held that the appellate authority was bound by Oasis Realty. The Orissa and Patna High Courts took a different view earlier, so the point is not settled everywhere.
2025
Penalty pre-deposit applies only from 1 October 2025
The appeal was against a penalty-only order under the WBGST Act. The Calcutta High Court held that the Finance Act, 2025 proviso, which requires 10% of the penalty, took effect on 1 October 2025 and cannot be applied backwards. Before that date there was no duty to deposit any part of a penalty, so the dismissal of the appeal was set aside.
2026
No penalty deposit where the SCN predates the amendment
The Delhi High Court held that the right of appeal vests when proceedings begin. Where the show cause notice was issued before 1 October 2025, the appellant does not have to deposit 10% of the penalty to appeal a penalty-only order. Later Delhi benches have applied this to appeals before the GSTAT.
2023
Section 5 of the Limitation Act applies
A Calcutta Division Bench held that Section 107 does not exclude Section 5 of the Limitation Act, so a delay beyond four months can be condoned for sufficient cause. The Allahabad High Court disagrees, and the Supreme Court has stayed this ruling in the Revenue’s SLP. File within the statutory time and treat condonation only as a fallback.
How to work out and pay the pre-deposit and file APL-01 in West Bengal
Find the appellate authority and the date of communication
If a West Bengal Commercial Taxes officer passed the order, the appeal lies to the State appellate authority. If a CGST Commissionerate passed it, the appeal lies to the central appellate authority. The three months under Section 107(1) run from the date the order was communicated. Check the “Additional Notices and Orders” tab on the portal as well.
Calculate the amount separately for CGST and SGST
Under Section 107(6), pay the whole of any tax, interest, fine, fee and penalty you admit. Then add 10% of the tax still in dispute, capped at Rs. 20 crore each for CGST and SGST. Interest and penalty do not count where tax is also disputed. For a penalty-only order, the 10% applies only if the proceedings began on or after 1 October 2025.
Pay from the cash or credit ledger, or link an old DRC-03
While filing APL-01, you can debit the electronic cash ledger or the electronic credit ledger against the demand. If you already paid through DRC-03, link that payment to the demand in DRC-03A under Rule 142(2B) so it counts. If the portal will not accept the payment, write to the proper officer and keep proof.
File APL-01 with grounds and documents
Go to Services, then User Services, then My Applications, then Appeal to Appellate Authority. Upload the impugned order, the DRC-07, the show cause notice and your reply, the statement of facts, the grounds and the ledger proof. Sign with DSC or EVC. No certified copy is needed if the order is already on the portal. APL-02 is the final acknowledgement.
If late, apply for condonation with specific reasons
Under Section 107(4), the appellate authority can allow one more month after the three months for sufficient cause. In Calcutta, S.K. Chakraborty allows condonation beyond that under Section 5 of the Limitation Act, but the ruling is under challenge in the Supreme Court. Give dated, documented reasons for every day of delay.
Insist on the deemed stay, and plan for the GSTAT
Once the pre-deposit is paid, Section 107(7) stays recovery of the balance. Write to the department if it debits your ledger or attaches your bank account anyway. If the first appeal fails, Section 112(8) requires a further 10% before the GSTAT. A GST lawyer can check the figures before you file.
How the pre-deposit reaches your APL-01
Whichever way the money is paid, it must be tied to the disputed demand before the appeal is complete.
Read the demand order
Note tax, interest, penalty and the admitted amount.
Compute CGST and SGST separately
Take 10% of the disputed tax within the ₹20 crore cap for each.
Choose the payment route
Cash ledger, credit ledger, or an earlier DRC-03 linked by DRC-03A.
File APL-01 online
Attach grounds, order, notice and reply, then sign with DSC or EVC.
Receive APL-02
This is the acknowledgement, and the balance demand is then deemed stayed under s.107(7).
Pre-deposit on disputed tax under Section 107(6)(b) and Section 112(8) of the CGST Act (work out CGST and SGST separately; the admitted amount is payable in full on top)
Mistakes that get GST appeals rejected or leave money stuck
Taking 10% of tax, interest and penalty together The 10% under Section 107(6)(b) is on the disputed tax only. Adding interest and penalty overstates the deposit and locks up money you did not have to pay.
Paying 10% of a penalty in an old case For penalty-only orders from proceedings that began before 1 October 2025, the Calcutta HC (Barjinder Singh Kohli) and the Delhi HC (Gaurav Jain) have held that no penalty pre-deposit is needed. Check the date of the show cause notice before you pay.
Leaving an earlier DRC-03 payment unlinked A voluntary DRC-03 payment counts towards the pre-deposit only once it is linked to the demand through DRC-03A. If you skip this step, the appellate authority may treat the deposit as unpaid.
Going to the High Court instead of paying the deposit Courts usually refuse a writ filed to get around the pre-deposit and send the party to the appeal. A writ petition in the Calcutta High Court generally succeeds only where natural justice was denied or the order was made without jurisdiction.
Discuss your GST appeal and pre-deposit
Each order has its own dates, amounts and payment history, and the position on penalty-only orders and on paying from the credit ledger has moved in 2025-26. Our chambers appears before GST appellate authorities and the Calcutta High Court. Bring the order, the show cause notice and your ledger statements, and we will go through the limitation, the figures and the route of payment with you. Outcomes depend on the facts and the law; nothing here is a promise of result.
Book a ConsultationEstablished by a distinguished alumnus of IIT Kharagpur, Patra’s Law Chambers stands as a beacon of legal expertise in Kolkata & Delhi. Know more →
Kolkata Office
NICCO House, 6th Floor, 2 Hare Street
Kolkata-700001 (Near Calcutta High Court)
Delhi Office
4455/5, First Floor, Gali Shahid Bhagat Singh
Main Bazar Road, Paharganj, New Delhi-110055
Contact
[email protected]
+91 890 222 4444 / +91 7003 715 325
Before and after 1 October 2025
The rule for orders demanding penalty alone changed, and courts have read the change as prospective.
Frequently asked questions on GST appeal pre-deposit
Under section 107(6), you must pay the full admitted amount of tax, interest, fine, fee and penalty, plus 10% of the tax still in dispute. The 10% is capped at ₹20 crore for CGST and ₹20 crore for SGST.
Not where tax is also disputed. For a penalty-only order from proceedings begun on or after 1 October 2025, 10% of the penalty is payable. Earlier proceedings are treated differently by the Calcutta and Delhi High Courts.
Several High Courts and a CBIC instruction of 6 July 2022 accept payment through the Electronic Credit Ledger. Some courts earlier disagreed, so verify the current position and the officer’s stand before relying on it.
Usually not. Under Rule 142(2B), an earlier DRC-03 payment can be linked to the demand through DRC-03A. If the portal does not allow it, write to the proper officer and keep proof of the payment.
Three months from the date the order is communicated, with one more month if the authority finds sufficient cause under section 107(4). The Calcutta High Court has allowed condonation beyond that in some cases.
Yes, for the balance demand. Section 107(7) treats it as stayed once the pre-deposit is paid. The Calcutta High Court has set aside ledger debits and bank attachments made afterwards.
No government fee is charged for APL-01. The cost is the pre-deposit itself. Fees for a second appeal to the GSTAT are different, so verify the current fee rules before filing there.
A further 10% of the remaining disputed tax under section 112(8), capped at ₹20 crore each, so about 20% in all with the first deposit. Check current time limits for orders passed before 1 April 2026.