Vehicle Seized Without Notice? The Supreme Court Says It Is Illegal
A finance company broke a truck’s steering lock at 1 a.m., sold it, and then demanded more money from the borrower. The Supreme Court closed his loans, ordered a refund with interest and awarded ₹10 lakh compensation. Here is what Hari Dutta Sharma v. State of U.P. means for every vehicle owner with a loan.
Your vehicle is gone. No notice, no call, no paper.
You missed a few EMIs. One morning your truck, car or bike is simply gone from where you parked it. Weeks later a letter arrives saying the vehicle has already been sold and you still owe money. Is a vehicle seized without notice lawful in India? On 16 September 2026, the Supreme Court answered that question clearly: no. A finance company that takes a vehicle by force, at night, without the notice its own agreement promises, cannot hide behind that agreement.
This guide explains the vehicle repossession rules in India after the judgment in Hari Dutta Sharma v. State of U.P. & Ors. (2026 INSC 998), decided by a Bench of Justice Pamidighantam Sri Narasimha and Justice Alok Aradhe — what the Court held, what a lender must do before and after repossession, and what you can do if your vehicle has been seized illegally by a bank, NBFC or recovery agent.
A lender’s right to repossess a financed vehicle is contractual, but it is not unlimited. It must follow the notice and procedure in the loan agreement and the RBI’s recovery guidelines, which carry statutory force. A seizure by force, at odd hours, without notice, violates Articles 14 and 21 of the Constitution and can attract compensation.
What happened to Hari Dutta Sharma’s truck
A small transporter from Ayodhya, a Tata SFC 407 truck, and a loan from Cholamandalam Investment and Finance Company Limited. Tap each date to see how the case unfolded.
Of a sanctioned loan of about ₹10.40 lakh, ₹9.36 lakh was disbursed for the truck, repayable in 75 monthly instalments and secured by hypothecation of the vehicle. A supplementary loan of about ₹1.04 lakh followed on 12 June 2021.
A recall-cum-demand notice was issued on 17 January 2022. The company repossessed the truck and sent a pre-sale letter on 13 June 2022. The borrower paid ₹86,726, promised to regularise the account, and the truck was released.
Notices dated 7 July 2022 and 22 December 2022 asked him to clear the dues or surrender the vehicle, warning that a surrendered vehicle would be sold and the proceeds adjusted.
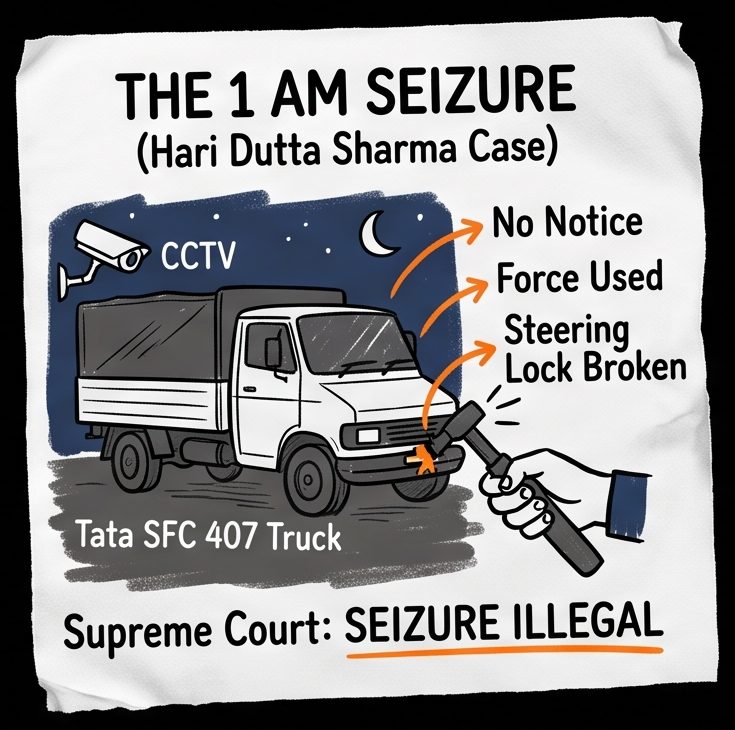
The company sent a pre-seizure intimation to the police station — but not to the borrower. That night, four unidentified men broke the steering lock and drove the truck away. Believing it stolen, he filed a lost-article report and an e-FIR the same day. No action followed.
The truck was sold on 31 August 2023 for ₹4,50,000. He complained to the Superintendent of Police on 8 September 2023. On 30 September 2023 a legal notice told him the truck had been repossessed and sold, and demanded a further ₹1,25,571. Traffic challans for the “sold” truck kept reaching him until February 2025.
His complaint under Section 156(3) CrPC was dismissed by the Chief Judicial Magistrate, Ayodhya on 23 September 2024 on the ground that the vehicle was confiscated for default. The Allahabad High Court dismissed his writ petition on 4 April 2025, holding he had approached the court late.
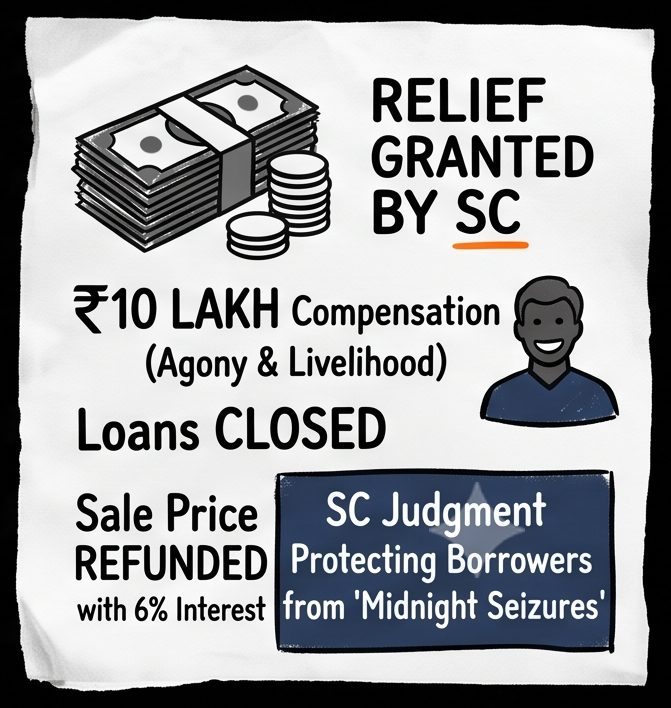
The Supreme Court condoned the delay, set aside the High Court’s order, held the seizure unlawful, and awarded refund with interest, closure of both loan accounts, ₹10 lakh compensation and ₹50,000 costs.
What the Supreme Court held
The judgment balances two legitimate interests: the lender’s need for an efficient way to recover a secured debt, and the borrower’s right to be treated fairly before he loses the very asset by which he earns his bread.
The right is contractual — but not unlimited
Relying on Orix Auto Finance v. Jagmander Singh and Sundaram Finance v. T. Thankam, the Court accepted that a financier may repossess if the agreement allows it. Because this self-help right operates without a court supervising it, it must be read with great caution and can never become a licence to seize by stealth, by force or at night.
RBI recovery guidelines are binding
Directions issued by the RBI under Section 35A of the Banking Regulation Act, 1949 carry statutory force. The Court traced two decades of RBI instruments — the 2003 Fair Practices Code for Lenders, the 2005 guidelines, the 2006 Fair Practices Code for NBFCs and the Master Circulars of 2008 to 2015.
A one-sided clause fails the test
A repossession clause that lets one party switch off the other party’s protection at will is an illusory promise. Such a clause is not in conformity with the RBI guidelines or the Indian Contract Act, 1872.
No notice means no right to repossess
The company’s own agreement required a seven-day notice before repossession. None was sent to the borrower. The right of repossession, being conditional on that notice, never accrued. Breaking a steering lock at 1 a.m. was not peaceful possession, and the possession memo did not even bear the borrower’s signature.
Delay was no ground to reject him
He filed an FIR on the very day and kept pursuing remedies in the belief that his truck had been stolen. The High Court was wrong to dismiss the case for delay without examining the merits or any prejudice to the company.
Articles 14 and 21 were violated
The borrower was a man of modest means who depended on the truck for his livelihood. Its arbitrary seizure deprived him of that livelihood in an unfair manner, violating Articles 14 and 21 of the Constitution, and entitling him to compensation.
Ten principles for every lender and every court
Reading the RBI’s Master Circulars, guidelines and clarifications together with ICICI Bank v. Prakash Kaur (2007), where the Court said banks cannot employ “goondas” to seize vehicles, the Bench set out ten principles “for the guidance of financial institutions and of the Courts”. Tap a number to read each one.
Lenders shall not, in the recovery of loans, harass borrowers by persistently bothering them at odd hours or by using muscle power.
You can read the RBI’s consolidated instructions, including the clarification on repossession of vehicles financed by NBFCs, in the RBI Master Circular — Fair Practices Code (updated 2015). The Court also noted that these guidelines had existed “only on paper”, and directed the RBI to take effective steps to secure genuine compliance by NBFCs and scheduled commercial banks.
Four defects the Court found in the repossession clause
Most borrowers never read Article 11 of their vehicle loan agreement. The Supreme Court did. Tap each card to see why the clause failed — then check your own agreement for the same wording.
It directly conflicts with the requirement that a repossession clause must provide a notice period before possession is taken.
An open licence to enter any place in search of the vehicle is contrary to the RBI guidelines and offends the requirement of a fair, lawful procedure for taking possession.
Leaving both the seizure and the sale wholly to the lender’s discretion places the borrower entirely at its mercy on the manner and timing of the sale.
A power to dispense with notice on the lender’s own view of “jeopardy” converts a floor of minimum protection into an illusory promise, defeasible by the very party it is meant to restrain.
What the Supreme Court awarded
Because the truck had been sold three years earlier, the Court declined to set aside the sale. Instead it directed the company to close both of his loan accounts, refund the sale price with interest, and compensate him for mental agony and loss of livelihood.
The ₹4,50,000 carries 6% simple interest from 31 August 2023 until payment. Slide to choose the payment date.
Total = refund with interest + ₹10,00,000 compensation + ₹50,000 costs. Illustrative simple-interest estimate, calculated to the 16th of each month.
Vehicle repossession rules in India: what the lender must do
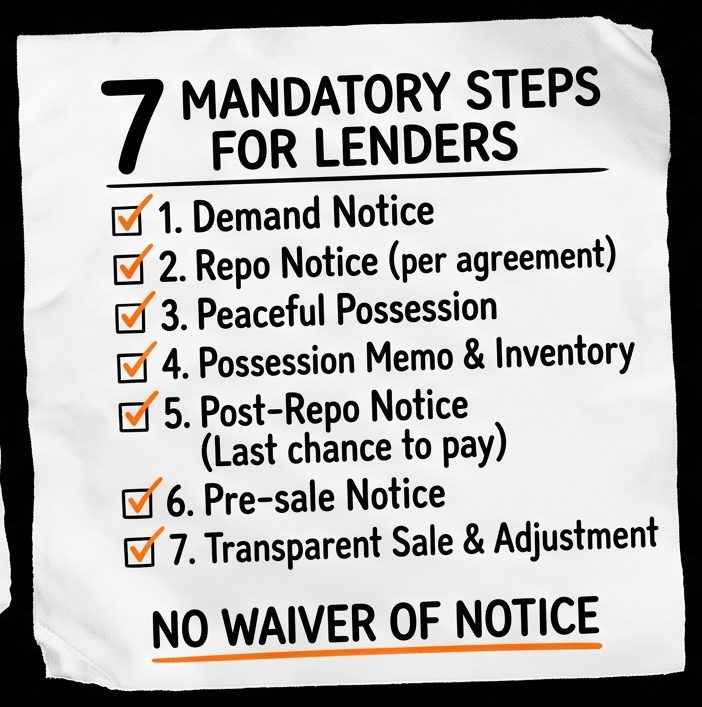
Putting the judgment and the RBI framework together, a lawful repossession of a financed vehicle ordinarily follows this sequence. If any step is missing in your case, note it down — it may be the core of your claim.
Reminders and a demand notice after default
The borrower is told in writing what is overdue and given an opportunity to pay.
Pre-repossession notice to the borrower
Sent to the borrower himself — not merely to the police station — for the period stated in the loan agreement (seven days in this case).
Peaceful possession, with memo and inventory
No force, no breaking locks, no night-time ambush. A possession memorandum and inventory should be prepared, ideally signed by the borrower. Recovery is ordinarily to happen at a central designated place.
Post-repossession notice — a final chance
After taking possession, the lender must give the borrower a last opportunity to pay and take the vehicle back.
Pre-sale notice and a transparent sale
The vehicle is sold by a fair procedure, the proceeds are adjusted against the loan, and any surplus is returned to the borrower.
Myth: the “three-month rule”
There is no fixed three-month rule for ordinary vehicle loans. Ninety days of overdue is when an account is classified as a Non-Performing Asset — an accounting milestone, not a licence to seize. Most vehicle repossessions are contractual, and there the notice period is whatever your agreement says, which the lender must actually honour.
The repossession clause in the loan or hypothecation agreement, read with RBI guidelines.
Section 13 of the SARFAESI Act, 2002, available only to eligible lenders within the Act’s thresholds.
As stated in the agreement — and it must actually be served on the borrower.
A 60-day demand notice under Section 13(2) before measures under Section 13(4).
Police and Magistrate, Consumer Commission, civil court, arbitration, RBI Ombudsman, and constitutional courts.
Securitisation Application before the DRT under Section 17, within 45 days.
Was your vehicle seizure lawful? Check in 60 seconds
Answer five questions about how your vehicle was taken. The result is indicative only and not legal advice — every case turns on its own documents and facts.
Your indicative result will appear here.
What to do if your vehicle is seized by a finance company
If your vehicle has been taken without notice or by force, act quickly and in writing. Hari Dutta Sharma won in the end largely because he filed an FIR the very same day and kept a clear paper trail.
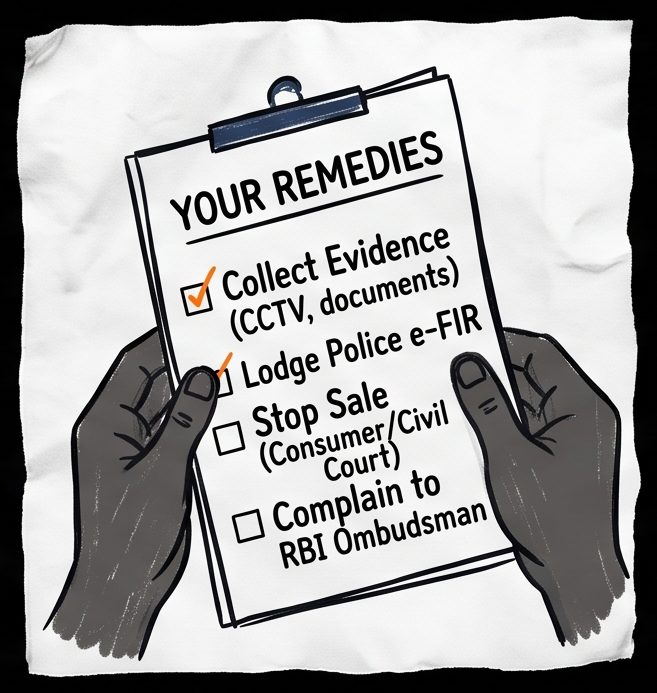
Collect and preserve everything
CCTV footage, witness details, photos, your loan agreement, the RC, the statement of account, and every notice received — or proof that none came. Note whether you signed any possession memo.
FIR, then SP, then Magistrate
Lodge an FIR or e-FIR. If the police do not act, send a written complaint to the Superintendent of Police under Section 173(4) BNSS, and then apply to the Magistrate under Section 175(3) BNSS. After this judgment, “the vehicle was taken for default” is no longer a sufficient answer.
Seek interim protection fast
Depending on the facts, seek an interim order from the Consumer Commission, an injunction from the civil court, or interim protection under Section 9 of the Arbitration and Conciliation Act, 1996 if the agreement contains an arbitration clause.
Lender grievance officer and RBI Ombudsman
Write to the lender’s grievance redressal officer. If there is no reply within 30 days or the reply is unsatisfactory, file a complaint under the RBI’s Integrated Ombudsman Scheme.
Waiting before reporting. A same-day FIR was the reason the Supreme Court rejected the delay argument. Silence for months makes it harder to show the seizure was forcible.
Treating this judgment as a loan waiver. It protects the manner of recovery; it does not wipe out genuine loan liability. The relief here flowed from the unlawful seizure, not from the debt disappearing.
Ignoring notices that do arrive. A borrower who receives and responds to notices is far better placed to prove what was — and was not — sent before seizure.
Going to the wrong forum. The DRT has a role only if the lender acted under SARFAESI. For contractual repossession, the remedies lie with the police, Magistrate, Consumer Commission, civil court, arbitration or constitutional courts.
Judgments relied on by the Supreme Court
2026
Hari Dutta Sharma v. State of U.P. & Ors.
2026 INSC 998 · decided 16.09.2026Seizure of a financed truck at 1 a.m., without the contractual seven-day notice, held unlawful; repossession clause found inconsistent with RBI guidelines and the Indian Contract Act; loans closed, refund with 6% interest, ₹10 lakh compensation and ₹50,000 costs. Download the full judgment (PDF).
2007
ICICI Bank Ltd. v. Prakash Kaur & Ors.
(2007) 2 SCC 711Recovery of loans and seizure of vehicles can only be made through legal means; banks cannot employ “goondas” to take possession of vehicles by force.
2006
Orix Auto Finance (India) Ltd. v. Jagmander Singh
(2006) 2 SCC 598A financier’s right to take possession of a financed vehicle is a matter of contract, where the agreement confers it.
2015
Sundaram Finance Ltd. v. T. Thankam
(2015) 14 SCC 444Relied on alongside Orix for the contractual nature of the repossession right, which is enforceable unless the contract is unconscionable or opposed to public policy.
2020
Internet and Mobile Association of India v. RBI
(2020) 10 SCC 274Directions issued by the RBI under Section 35A of the Banking Regulation Act possess statutory force and bind banking companies.
Supreme Court of India, Civil Appellate Jurisdiction, 2026 INSC 998 (24 pages).
Facing an illegal vehicle seizure? Contact us
If your vehicle has been seized without notice, taken by recovery agents at night, or sold without a fair opportunity to pay — or if you are facing any similar issue with a bank or finance company — you can contact us in this regard. We will review your loan agreement, the notices you received and the circumstances of the seizure, and explain your options.
Call +91 890 222 4444WhatsApp / Phone: +91 890 222 4444 · +91 7003 715 325 · Email: [email protected]
Kolkata Office
NICCO House, 6th Floor, 2 Hare Street
Kolkata-700001 (Near Calcutta High Court)
Delhi Office
4455/5, 1st Floor, Gali Shahid Bhagat Singh
Paharganj, New Delhi-110055
Contact
[email protected]
+91 890 222 4444 / +91 7003 715 325
Frequently asked questions
Not where your loan agreement and the RBI guidelines require notice, which they ordinarily do. In Hari Dutta Sharma, the Supreme Court held that because the seven-day notice was never given, the right of repossession never arose. A clause letting the lender waive notice at its own discretion was found unfair.
There is no single statutory number for contractual repossession. RBI requires the repossession clause to state a notice period, and the lender must follow it. Check the repossession clause in your own agreement. If a lender acts under SARFAESI, a 60-day demand notice under Section 13(2) is mandatory.
Seizure must be peaceful and lawful. The Court described a 1 a.m. seizure by breaking the steering lock as bearing every mark of the “goondaism” it had condemned earlier. Recovery should ordinarily take place at a designated place, not by ambush.
Send a written complaint to the Superintendent of Police under Section 173(4) BNSS, then apply to the Magistrate under Section 175(3) BNSS. This judgment is directly useful, because the Magistrate in that case had wrongly rejected the complaint on the ground that the vehicle was confiscated for default.
Yes, courts and consumer commissions can award compensation. Here the Supreme Court awarded ₹10 lakh, plus refund of the sale price with interest and closure of both loan accounts. The amount in any case depends on its facts, especially loss of livelihood and the conduct of the lender.
No. The judgment protects the manner of recovery, not the debt itself. The loan accounts were closed in this case as part of the relief for an unlawful seizure — a genuine borrower still owes what is lawfully due.
Only if the lender has taken possession under the SARFAESI Act, in which case a Securitisation Application under Section 17 must be filed within 45 days. Most vehicle repossessions are contractual, and there the DRT has no role.
The principles apply to any financed vehicle repossessed by a bank or NBFC regulated by the RBI — car, bike or commercial vehicle. The compensation in this case was shaped by the loss of the borrower’s livelihood, so the relief in another case will depend on its own facts.