Understanding Hiba: Gift under Muslim Law
Hiba is the Muslim law of gift. It is an immediate, voluntary transfer of property without payment. This guide explains the three essentials, the types of gift, the courts’ approach to possession, and how a Hibanama is used as evidence.
What is Hiba, and when is a Muslim gift valid?
In Muslim law, a gift (Hiba) is the transfer of property made immediately and without any exchange by one person to another, and accepted by or on behalf of the other. Muslim law does not require a written or registered document for a valid gift, provided three conditions are met together: a clear declaration by the donor (Ijab), acceptance by the donee (Qabul), and delivery of possession (Ikab-at-qabz). Section 129 of the Transfer of Property Act, 1882 saves the Muslim law of gift from the rule that a gift of immovable property needs a registered instrument.
Possession is where most disputes arise. The Supreme Court has repeatedly held that if the three essentials are proved, the gift stands even when it was never registered, and that writing it down does not by itself make registration compulsory (Hafeeza Bibi v. Shaikh Farid, 2011). A gift that is only claimed decades later, with no mutation or other sign that possession passed, is hard to prove. Disputes over a gift of land or a house are usually decided on evidence, so they are best taken to a court with that in mind, such as through our Calcutta High Court advocate consultation page. Please verify the current position on your own facts before acting.
Muslim gift versus a general gift under the Transfer of Property Act
The rules on form differ sharply, and this is why Hiba is often misunderstood.
Which gift situation looks like yours?
Pick the option closest to your facts to see how Muslim law usually treats it. This is general information, not advice. The outcome depends on the documents, the school of law and the evidence.
Choose one of the options above.
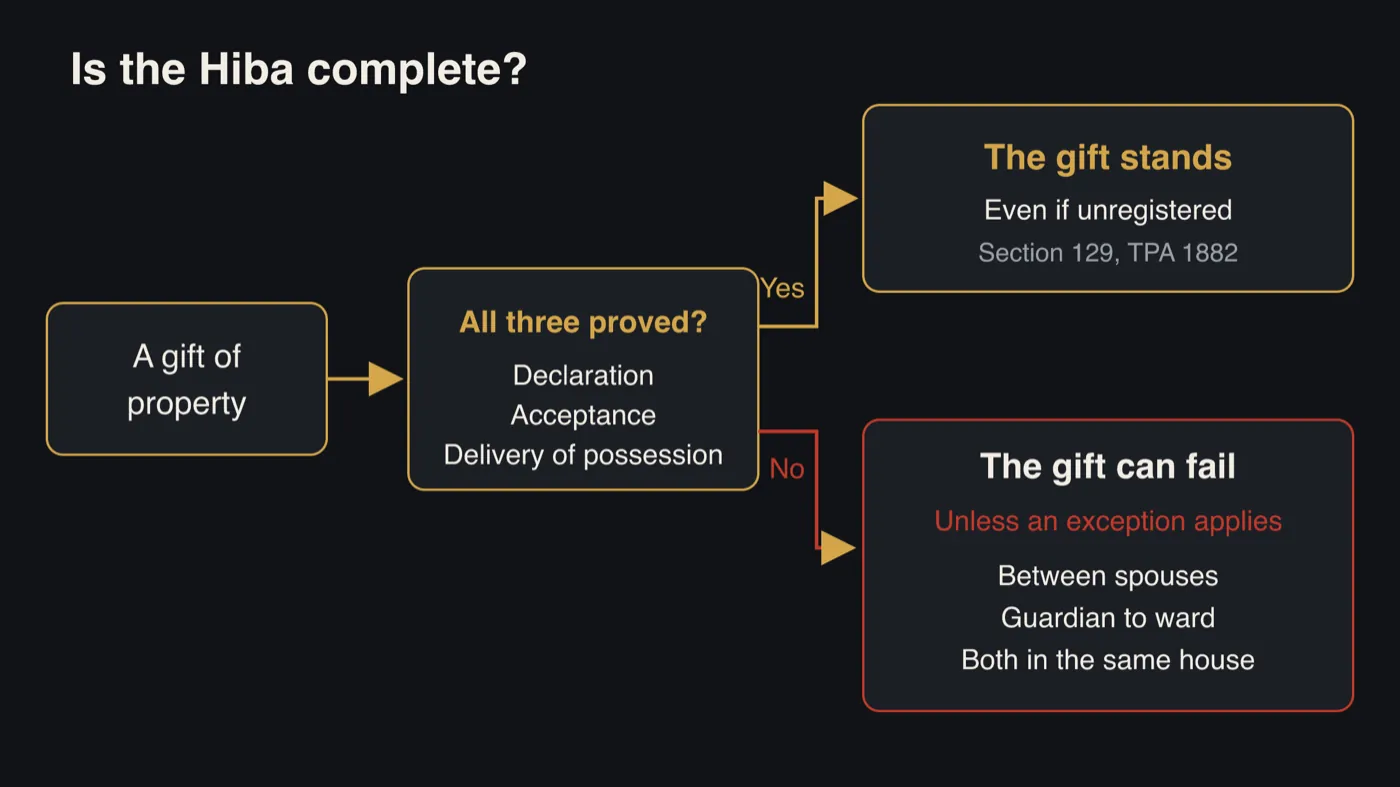
How a valid Hiba comes into being
A Muslim gift is completed in stages. Missing a stage is the most common reason a gift is later challenged.
The donor must be a Muslim of sound mind and age of majority, and the owner of the property. The property must exist and be in the donor’s ownership at the time. A gift of something to be produced in the future is void.
The donor clearly declares an intention to give the property now, without any exchange. Words can be oral or written, but they must be unambiguous.
The donee accepts, expressly or by conduct. For a minor or a person of unsound mind, the guardian accepts. For a case involving a disputed family property, you may want to read about Calcutta High Court advocate consultation.
The donor must divest themselves and put the donee in possession, physical or constructive. Gifts between spouses, from a guardian to a ward, or where both live in the same house need no physical move.
A Hibanama is not mandatory, but it is valuable evidence. Handing over the title documents and mutating the revenue or municipal records helps show that the gift was acted upon. Family disputes arising from a gift may also touch matrimonial and family law.
The court looks at witnesses, possession, mutation and conduct of the parties. Important appeals may reach the High Court or the Supreme Court.
Four ideas that decide most Hiba disputes: tap a card
A gift made for a consideration already received. It is treated like a sale, and the rules for a pure gift, including delivery of possession, apply differently.
A gift made on a stipulation that the donee will give something in return in future. It becomes a sale once the return is made, and until then it can be withdrawn.
A grant of the right to use the property, its usufruct, for a limited time. Ownership does not pass, and the grant is revocable.
A gift made during a death-illness is treated like a Will. It is limited to one-third of the estate unless the heirs consent.
Kinds of gift and how possession is treated
Simple gift (Hiba)
A gratuitous transfer with nothing expected in return. A Muslim may gift the whole of their property during their lifetime, unlike a Will, which is limited to one-third. The gift is complete once declaration, acceptance and possession are all present.
Hiba-bil-Iwaz and Hiba-ba-shart-ul-Iwaz
Hiba-bil-Iwaz is a gift for a consideration already received, and it is often treated like a sale. Hiba-ba-shart-ul-Iwaz is a gift made with a stipulation for a return in future. Both differ from a simple gift in how the law views the exchange.
Areeat and Sadaquah
Areeat is a revocable grant of the right to use the property for a limited time, without transferring ownership. Sadaquah is a gift made with a religious or charitable motive, and once completed by delivery of possession it cannot be revoked.
When physical delivery is not needed
Courts accept that a gift can be complete without the donor leaving the premises in some situations. For a family property gift or a dispute about possession, our matrimonial and family law services page shows how we handle related matters.
What helps prove a Hiba later
- A clear record of the declaration (Ijab), ideally with witnesses
- Acceptance (Qabul) by the donee, or by a guardian for a minor
- Proof that possession actually passed, such as handing over title papers
- Mutation of the donee’s name in municipal or revenue records
- A Hibanama (memorandum of gift) kept as evidence, even though registration is not compulsory
Supreme Court rulings on Hiba (gift under Muslim law)
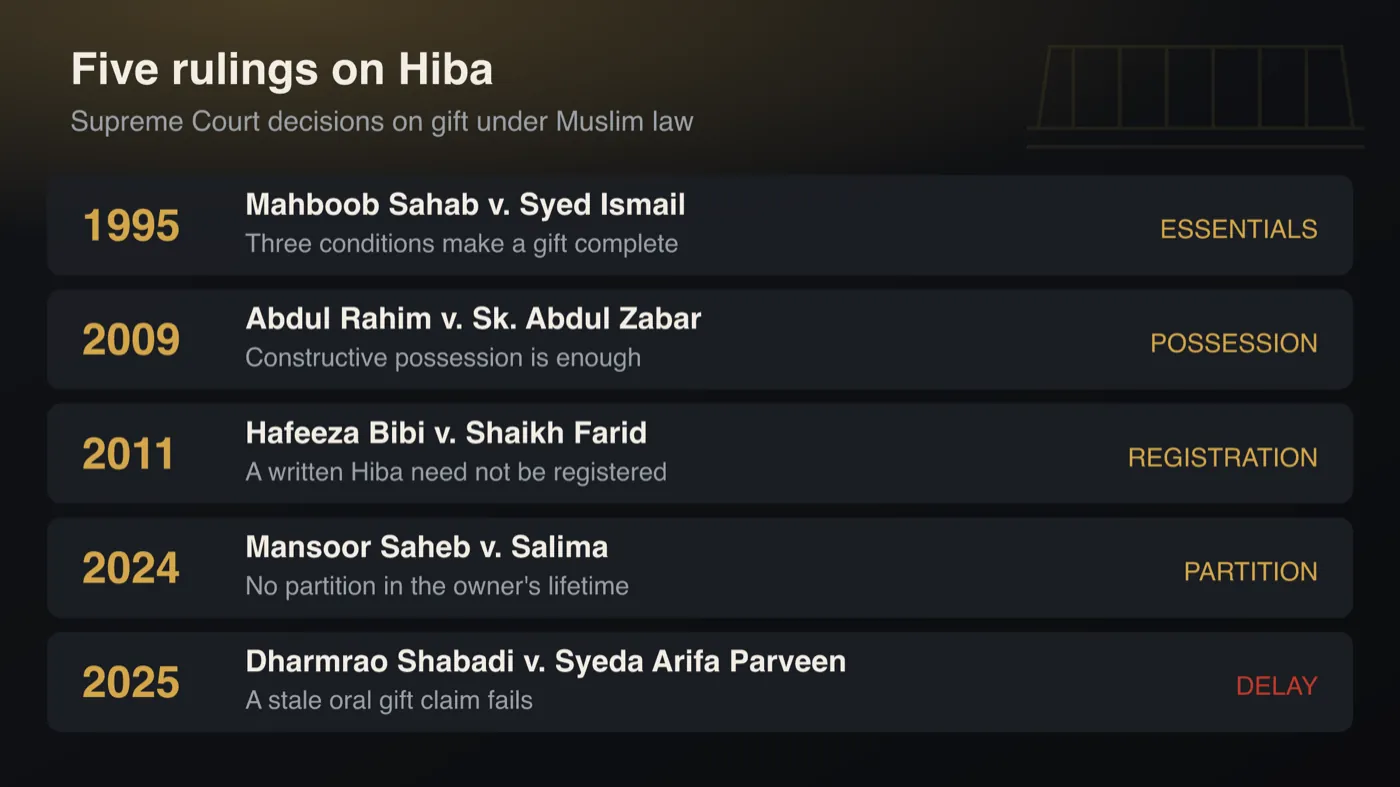
Indian courts apply the three essentials of Hiba strictly: declaration, acceptance and delivery of possession. These five Supreme Court decisions settle how a gift under Muslim law is made, proved and challenged.
1995
Three conditions make a gift complete
Relying on Mulla’s Principles of Mahomedan Law and the Privy Council’s ruling in Mohammad Abdul Ghani v. Fakhr Jahan Begam, the Court held that a valid Muslim gift needs a declaration by the donor, acceptance by or for the donee, and delivery of possession. Writing is not essential. The donor must fully give up ownership and control of the property.
2009
Constructive possession satisfies the Hiba rule
The donor’s property was let out to tenants, so the Court held that handing over constructive possession was enough and physical handover was not needed. The donor’s own application for mutation helped show that delivery had taken place. A suit to cancel the gift was held barred by limitation under Article 59 of the Limitation Act, 1963.
2011
A written Hiba need not be registered
Section 129 of the Transfer of Property Act, 1882 preserves Muslim law and excludes Section 123. An oral gift that meets all three essentials is complete. If it is later written down, the paper is a record of the declaration, not an instrument of gift under Section 17 of the Registration Act, 1908, so registration is not compulsory.
2024
No partition during the owner's lifetime
Heirs have no vested right in a Muslim’s property while the owner is alive, so a family partition during the owner’s lifetime is unknown to Muslim law. Such a transfer can stand only if it is proved to be a valid gift. The Court also said mutation entries serve revenue purposes and do not by themselves confer title.
2025
A stale oral gift claim fails
The Court set aside a Karnataka High Court ruling that had accepted an unregistered oral gift raised long after the event. An oral Hiba holds only when possession is actually delivered and the gift is acted upon. A claim that cannot show this, and is brought decades later, fails on proof and on limitation.
How to make and record a valid Hiba
Check the donor's capacity and title
The donor must be an adult of sound mind, acting freely, and must own the property and hold it on the date of the gift. A gift made during a last illness (marz-ul-maut) is treated like a will and is limited to one-third of the estate. Check that the property is free of disputes and loans first.
Make a clear declaration (Ijab)
The donor declares, in words that leave no doubt, that the property is given now and without anything in return. Make the declaration in front of at least two reliable witnesses, who can later confirm the date, the words used and the property described.
Record the donee's acceptance (Qabul)
The donee accepts, either in words or by conduct. If the donee is a minor or of unsound mind, the lawful guardian accepts on their behalf. A gift to a person not yet born, or to a person who has died, is void.
Deliver possession (Qabza)
Hand over actual possession, or constructive possession where it fits: keys, original title deeds, and a letter telling tenants to pay rent to the donee. The narrow exceptions for spouses, guardian and ward, and a shared residence should be confirmed for your facts.
Write a Memorandum of Oral Gift (Hibanama)
Record the completed oral gift in a memorandum signed by the donor, the donee and the witnesses. Under Section 129 of the Transfer of Property Act it does not need registration. Check with the local registry whether stamp duty applies in your state before you sign.
Get the property mutated and act on the gift
Apply to the municipal body or land records office to mutate the property into the donee’s name, and pay taxes in the donee’s name from then on. If the gift is challenged later, the Calcutta High Court advocate consultation page explains how the firm handles property disputes.
What helps prove a Hiba in court
Because an oral gift leaves no deed, evidence of the three essentials carries the case.
People who heard the donor clearly declare the gift and the donee’s acceptance.
A written record of the oral gift, signed by donor and donee, with a clear schedule of the property.
Evidence such as who lives in, rents out or manages the property after the gift.
Transfer of the donor’s original papers to the donee supports delivery.
Not proof of title by itself, but strong evidence that the gift was acted upon.
Bills and receipts after the gift show the donee acting as owner.
Common mistakes that make a Hiba invalid
Registering a deed but never giving possession Registration cannot cure the lack of delivery of possession. If the donor keeps full control of the property, the gift can be held incomplete even with a registered deed.
Leaving mutation for years Mutation does not create title, but courts treat it as strong evidence that the gift was acted upon. An oral gift raised decades later, with nothing done in the records, has repeatedly failed in court.
Calling a family division a gift Dividing property among heirs while the owner is alive is not a partition under Muslim law. Each share must separately meet all three essentials of Hiba, or it will not stand.
Putting conditions on the ownership itself A condition that restricts the donee’s ownership, such as a ban on selling, is generally void and the gift takes effect without it. For family property matters, read the firm’s matrimonial and family law services page, or ask about a Supreme Court advocate consultation for appeals.
Planning a Hiba or facing a dispute over a gift?
Whether you want a Hibanama drafted as a record of an oral gift, or a gift is being challenged in a property dispute, the documents and the facts about possession matter. Patra’s Law Chambers can review your papers and advise on the steps open to you in the civil courts and the High Court. Every matter is different, and no outcome can be promised. You can also read about our Supreme Court advocate consultation work.
Book a ConsultationEstablished by a distinguished alumnus of IIT Kharagpur, Patra’s Law Chambers stands as a beacon of legal expertise in Kolkata & Delhi. Know more →
Kolkata Office
NICCO House, 6th Floor, 2 Hare Street
Kolkata-700001 (Near Calcutta High Court)
Delhi Office
4455/5, First Floor, Gali Shahid Bhagat Singh
Main Bazar Road, Paharganj, New Delhi-110055
Contact
[email protected]
+91 890 222 4444 / +91 7003 715 325
Frequently asked questions on Hiba, the gift under Muslim law
No. An oral gift is valid under Muslim law if declaration, acceptance and delivery of possession are proved. Section 129 of the Transfer of Property Act, 1882 saves Muslim gifts from the registration rule that governs other gifts. A written Hibanama is still wise as evidence.
During life, yes. Unlike a Will, which is limited to one-third without the heirs’ consent, a lifetime gift can cover the whole property. A gift made in death-illness (Marz-ul-maut) is different and is treated like a Will.
They are declaration by the donor (Ijab), acceptance by the donee (Qabul) and delivery of possession (Ikab-at-qabz). All three must be present. The Supreme Court has repeatedly stressed that possession is central to a valid Hiba.
No. Section 129 of the Transfer of Property Act, 1882 leaves Muslim gifts outside the registration rule. In Hafeeza Bibi v. Shaikh Farid (2011), the Supreme Court held that writing a gift down does not make registration mandatory. Verify local revenue practice for mutation.
Delivery can be constructive in some cases: a gift between spouses living together, a gift from a father or guardian to a minor, or where the donor and donee already live in the same house. Each case depends on its facts, so verify with a lawyer.
Yes to both. Religion is not a bar for the donee, and a gift can be made to a juristic person such as a mosque. A gift to a person not in existence, such as an unborn child, or to a deceased person is void.
It is difficult. Under Hanafi law, revocation generally needs the donee’s consent or a court decree. Some gifts, such as those to a spouse or close relatives, cannot be revoked, and a completed Sadaqah cannot be revoked at all.
Mushaa is an undivided share in property. Under Sunni (Hanafi) law, a gift of an undivided share in divisible property is irregular until the share is separated and possession is given. Under Shia law, it is generally valid.