Income Tax Appeal Lawyer in Kolkata: CIT(A), ITAT, High Court
Assessment orders, reassessment notices, penalty orders and tax demands each have their own appeal route and their own time limit. Patra’s Law Chambers represents assessees at the Commissioner (Appeals), the Income Tax Appellate Tribunal and the Calcutta High Court, including NRIs who deal with Indian tax from abroad.
How an income tax appeal moves from the CIT(A) to the High Court
An assessment order or penalty order is not the last word. Under the Income-tax Act, 1961, an assessee can appeal to the Commissioner of Income-tax (Appeals) under section 246A by filing Form 35, ordinarily within 30 days of the order or demand notice (section 249). A further appeal lies to the Income Tax Appellate Tribunal under section 253, and a substantial question of law can be taken to the High Court under section 260A. Orders for years from 1 April 2026 onward fall under the Income-tax Act, 2025, so the correct Act and section numbers have to be checked for each year. The official Income Tax Department portal carries the forms, the e-filing steps and the e-proceedings record.
Most appeals are decided on the record, so the quality of the grounds and the paper book matters from the first filing. Our work covers drafting Form 35 grounds, filing the appeal and any condonation of delay application, applying for stay of demand, and arguing the appeal. It also covers reassessment notices, where the income tax lawyer service page explains notices and assessments in general. Appeals before the Calcutta High Court are argued by Sudip Patra himself, as described on the Calcutta High Court advocate page. Supreme Court matters are filed through his Supreme Court connection. Every case is assessed on its own papers, and no outcome can be promised.
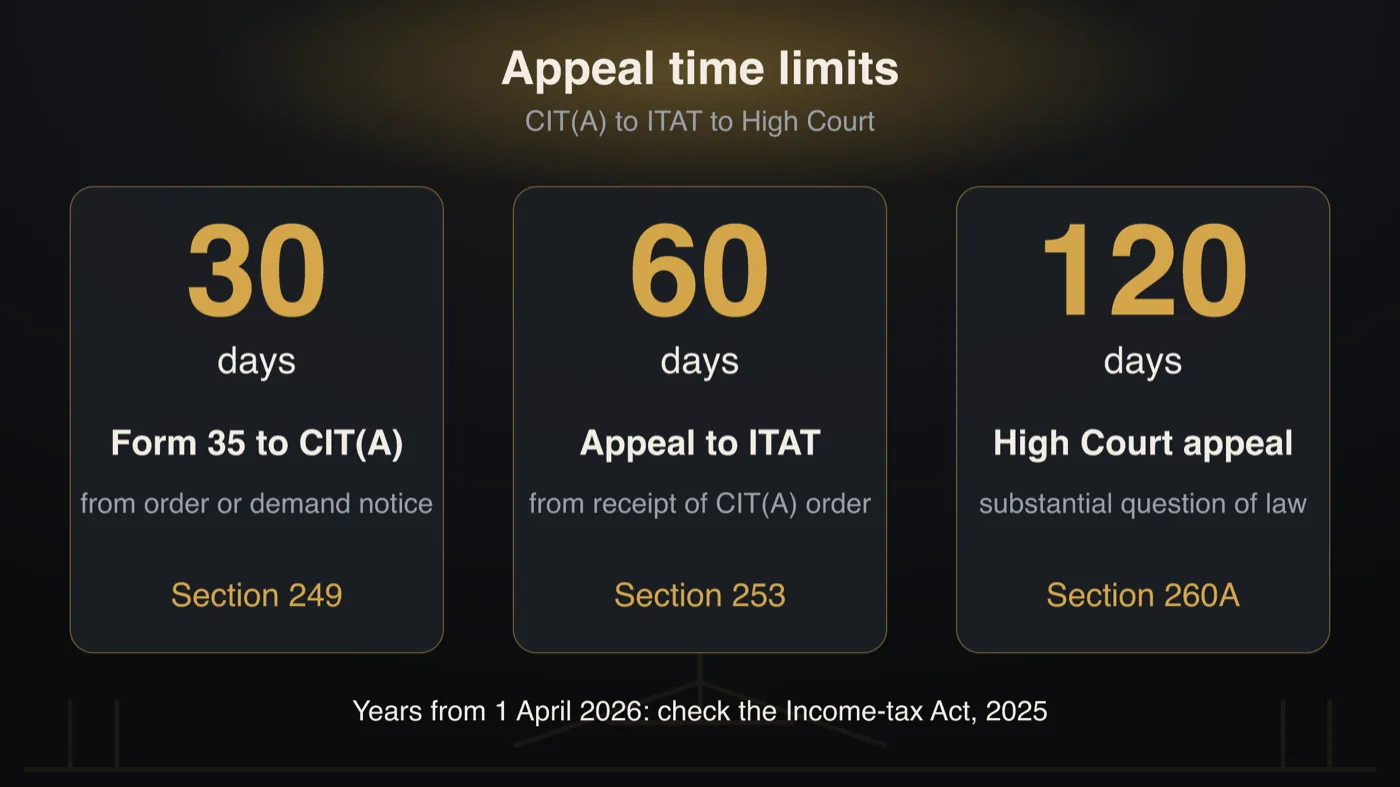
The four dates to keep in front of you
These are the usual periods, counted from service or communication, so confirm the date on the record.
Short explainers from Adv. Sudip Patra
More short explainers on our YouTube channel: Patra’s Law Chambers on YouTube ↗
Which income tax paper have you received?
Pick the paper in your hand to see the forum and the usual next step. This is general information, not advice. The right course depends on the exact order, its date and the year it covers.
Choose one of the options above.
How an income tax dispute usually moves up the ladder
Each step has its own form, time limit and forum. Missing a limit can close a route, so the dates matter more than anything else.
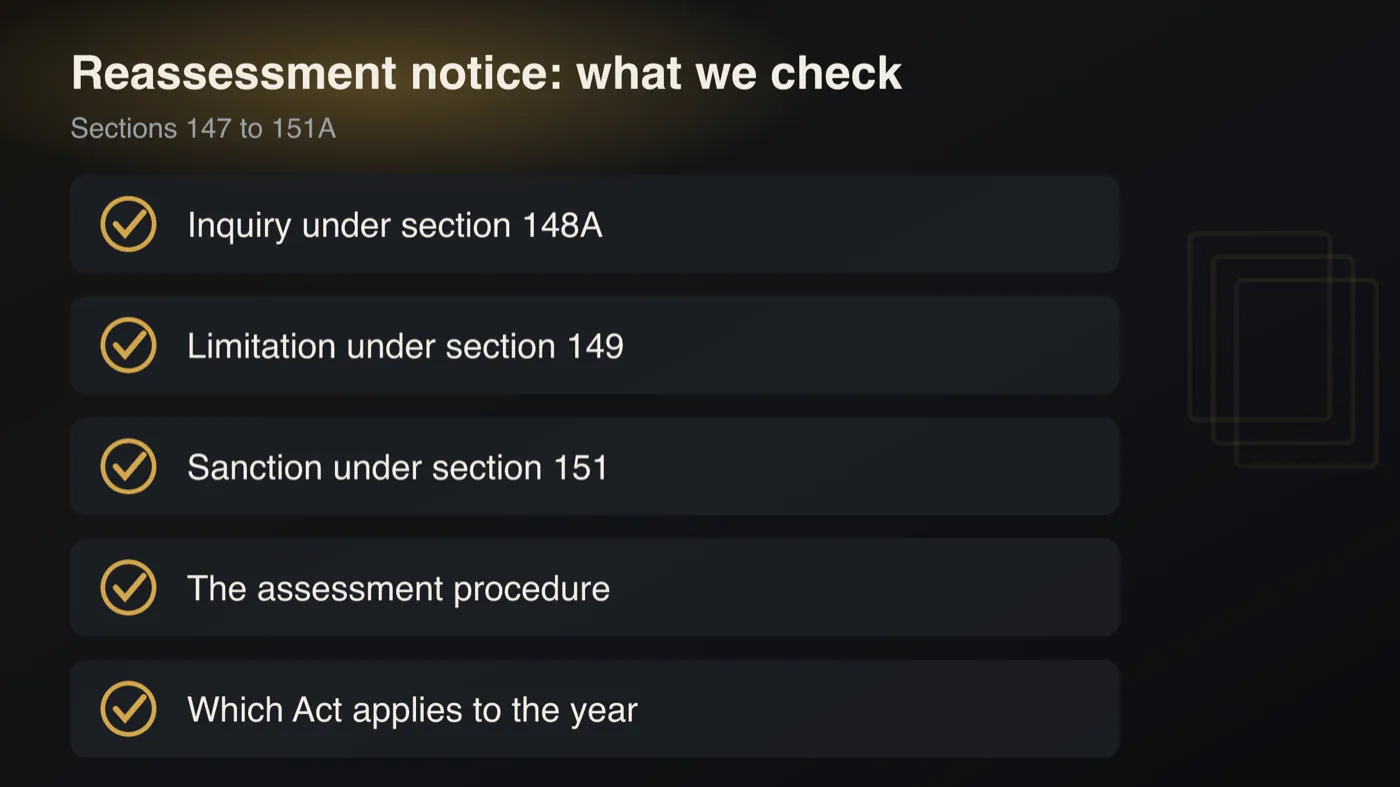
The dispute starts with a notice, an assessment order, an intimation or a penalty order. For a reassessment notice, read the reasons carefully and check the years, the limits and the sanction. Our income tax lawyer page explains the common notices.
A demand can be recovered while the appeal is pending, so a stay application usually goes in early. The Assessing Officer and the Principal Commissioner are approached first. Where the demand is high or the reasons are poor, a writ petition may be considered.
Form 35 is filed under Section 246A with the grounds, a statement of facts and the prescribed fee where applicable. A late appeal needs an application to condone delay under Section 249(3), with reasons. The CIT(A) can confirm, reduce, enhance or annul the assessment.
Form 36 is filed under Section 253 against the CIT(A) order. The Tribunal is the last fact-finding authority, so the paper book and evidence matter here. A stay by the Tribunal under Section 254(2A) is limited in time, so the date of hearing should be watched.
A Section 260A appeal needs a substantial question of law drawn from the ITAT order. Writ petitions against reassessment or recovery are also heard here. See our Calcutta High Court advocate page for how these matters are handled.
A further challenge lies by special leave petition under Article 136, which the Court may or may not entertain. Supreme Court matters are filed through the chambers’ Supreme Court connection. More is on the Supreme Court advocate page.
Three things to check before you appeal. Tap a card
The Finance Act, 2026 inserted Section 147A on the faceless Assessing Officer for reassessment. In Asst. Commissioner of Income Tax v. Aristo Pharmaceuticals Pvt. Ltd., 2026 LiveLaw (SC) 436 (10 April 2026), the Supreme Court gave no view on its validity and sent the writs back to the High Courts. Verify the present position.
Filing an appeal does not by itself stop recovery of the demand. A separate stay application with the reasons and the payment position is usually needed. Keep copies of every application and reply.
The High Court appeal under Section 260A is confined to a substantial question of law. Evidence and explanations should therefore be complete before the CIT(A) and the Tribunal, not left for later.
Income tax appeal work we handle
Appeals before the CIT(A)
First appeals against assessment orders, intimations and penalty orders. We prepare the statement of facts and grounds, the paper book and the written submissions, and apply to condone delay where the 30-day period has passed with good reason.
Appeals before the Income Tax Appellate Tribunal
Appeals by the assessee, and cross-objections where the department appeals, before the Kolkata Benches of the Tribunal. This covers drafting Form 36 and the grounds, and arguing the appeal on facts and law. Rectification under section 254(2) is considered where a mistake apparent from the record exists.
Reassessment notices and challenges
Notices under section 148 after the inquiry under section 148A are checked for limitation under section 149, sanction under section 151 and the assessment procedure. The Supreme Court order in Asst. Commissioner of Income Tax v. Aristo Pharmaceuticals Pvt. Ltd., 2026 LiveLaw (SC) 436 (10 April 2026) is relevant to the new section 147A and should be read in full.
Section 260A appeals and writ petitions
Appeals on a substantial question of law against ITAT orders, and writ petitions under Article 226 where a notice or order is without jurisdiction or breaches natural justice. We also advise on whether an appeal or a writ is the right route.
What the work includes
- Stay of demand: application to the Assessing Officer and the CIT(A) under section 220(6), and before the ITAT and High Court where needed
- Penalty appeals under sections 270A, 271 and related provisions
- Condonation of delay in filing appeals
- Responses to e-proceedings notices on the Income Tax portal
- Tax matters of NRIs and returning residents, with documents handled online
- Advice on GST disputes through the GST lawyer page
Supreme Court rulings that shape income tax appeals and reassessment
These decisions decide how reopening notices are tested, how stay of demand works, and how far the Tribunal can protect you while an appeal is pending. Each has been checked against reported sources; read the full text before relying on it in your own matter.
2002
Reasons must be given and objections decided
For reopening under the old Section 147 procedure, the Supreme Court held that the assessee may ask for the reasons recorded for reopening and file objections. The Assessing Officer must decide those objections by a speaking order before going ahead with the reassessment. High Courts and the Tribunal still apply this safeguard when they test reopening of older years.
2022
Old-form notices treated as Section 148A notices
About 90,000 reassessment notices were issued after 1 April 2021 under the old Section 148. The Court invoked Article 142 and treated them as show-cause notices under the new Section 148A(b), so the new procedure applies to them. Later High Court rulings read the order narrowly, so whether it covers your notice depends on its facts.
2024
Time limits govern every reopening notice
A bench of three judges held that the Taxation and Other Laws (Relaxation and Amendment of Certain Provisions) Act, 2020 (TOLA) applies to reassessment. It held that the time remaining at the date of the original notice carries forward under Ashish Agarwal, and that Section 151 sanction from the correct authority is mandatory. On that reasoning, notices issued after 1 April 2021 for assessment year 2015-16 were held time-barred.
2026
Section 147A disputes sent back to High Courts
The Finance Act, 2026 (Act No. 4 of 2026) inserted Section 147A, deemed in force from 1 April 2021, so that jurisdictional Assessing Officers can issue Sections 148 and 148A notices. The Court set aside the High Court rulings that had quashed such notices. It gave no view on whether 147A is valid, allowed writs to be amended, stayed reassessment on conditions and remitted the matters.
2018
The 20% deposit is not a rigid rule
The CBDT office memoranda of 29 February 2016 and 31 July 2017 direct a stay of disputed demand on payment of 20 percent. The Supreme Court held that this does not bind the authorities’ discretion under Section 220(6). In a fit case, for example where the assessee has a strong prima facie case or faces financial hardship, a smaller deposit, or none, can be ordered.
2021
Tribunal stay need not lapse automatically
Under the third proviso to Section 254(2A), a stay granted by the ITAT ended after 365 days even when the assessee had caused no delay. The Supreme Court held that this breached Article 14 to that extent. Where the assessee is not responsible for the delay, the Tribunal may extend the stay beyond 365 days.
How an income tax appeal moves from the CIT(A) to the Calcutta High Court
Read the order and the demand notice
Check the assessment, reassessment or penalty order and the Section 156 demand notice. Note the date of service, the assessment year and every addition. Appeals for tax years starting before 1 April 2026 stay under the Income-tax Act, 1961, even though the Income-tax Act, 2025 is now in force.
File Form 35 before the CIT(A)
File the appeal online in Form 35 under Section 246A within 30 days of service of the demand, as Section 249 requires, and pay the prescribed fee. Section 249(4) requires the admitted tax, or advance tax where no return was filed, to be paid first. If you are late, file a reasoned application for condonation of delay.
Apply for stay of demand
Ask the Assessing Officer, under Section 220(6), to treat you as not in default while the appeal is pending, and give reasons. If that is refused, move the Principal Commissioner. The CBDT guideline is a 20 percent deposit, but under LG Electronics the authority can accept less in a fit case.
Appeal to the ITAT in Form 36
Against the CIT(A)’s order, file Form 36 before the Income Tax Appellate Tribunal, Kolkata Benches, within 60 days under Section 253(3). The department may file cross-objections in Form 36A within 30 days. The ITAT is the last forum that decides facts, so the paper book should contain every document you rely on.
Appeal to the Calcutta High Court
Under Section 260A, an appeal from an ITAT order lies to the High Court within 120 days, but only on a substantial question of law. Where a notice is issued without jurisdiction, for example a reopening notice under Sections 148 and 148A, a writ petition under Article 226 may be filed instead.
Supreme Court, if needed
An appeal or special leave petition against a High Court judgment goes to the Supreme Court. Sudip argues these matters himself and files them through his Supreme Court connection. The limitation period and the questions of law should be checked as soon as the High Court judgment is received.
From assessment order to the High Court
An income tax dispute normally climbs one forum at a time.
Order or demand notice
The Assessing Officer’s assessment, intimation or penalty order starts the clock.
CIT(A) appeal
Form 35 is filed under Section 246A with a stay application for the demand.
ITAT appeal
Form 36 is filed under Section 253 against the CIT(A) order.
High Court appeal
Section 260A appeal lies on a substantial question of law.
Supreme Court
A special leave petition under Article 136 may be filed, subject to the Court’s discretion.
Indicative deposit for stay of disputed demand: CBDT office memoranda of 29.02.2016 and 31.07.2017 (Section 220(6)) and the first proviso to Section 254(2A), Income-tax Act, 1961
Mistakes that cost appeals and add to the demand
Missing the 30-day window for Form 35 Delay can be condoned only for sufficient cause, shown with dates and documents. A bare request is often refused, and the demand then becomes final.
Ignoring a Section 148A show-cause notice If no reply is filed within the time given, you lose the chance to object to reopening at the start. Reply to every ground, and ask for the information and approval the notice relies on.
Not applying for stay of demand Filing an appeal does not stop recovery by itself. Without a stay application under Section 220(6), refunds can be adjusted against the demand and bank accounts attached.
Filing new evidence at the ITAT without a reason Documents not produced earlier need an application for additional evidence that explains why they were missing. They should also have been raised in the grounds before the CIT(A) where possible.
Discuss your income tax appeal
If you have received an assessment order, a reassessment notice, a penalty order or a demand notice, the time limit for appeal runs from the date of the order or service. Bring the order, the notices, your return and the computation, and the correct forum and timeline can be explained to you from the papers. The firm acts for clients in Kolkata, across West Bengal and for NRIs abroad. Outcomes depend on the facts and the law, and none can be promised.
Book a ConsultationEstablished by a distinguished alumnus of IIT Kharagpur, Patra’s Law Chambers stands as a beacon of legal expertise in Kolkata & Delhi. Know more →
Kolkata Office
NICCO House, 6th Floor, 2 Hare Street
Kolkata-700001 (Near Calcutta High Court)
Delhi Office
4455/5, First Floor, Gali Shahid Bhagat Singh
Main Bazar Road, Paharganj, New Delhi-110055
Contact
[email protected]
+91 890 222 4444 / +91 7003 715 325
Appeal or writ: what each route is for
The two routes answer different problems, and the right one depends on the defect in the order.
Frequently asked questions about income tax appeals in Kolkata
Form 35 is usually filed within 30 days from service of the notice of demand or the order, under Section 249(2). A late appeal can be admitted only if the CIT(A) is satisfied there was sufficient cause for the delay under Section 249(3). Verify the service date from the record.
An appeal to the Income Tax Appellate Tribunal in Form 36 is generally filed within 60 days from the date the CIT(A) order is communicated, under Section 253(3). The other side may file cross-objections within 30 days of receiving notice of the appeal, under Section 253(4).
Yes, under Section 260A, within 120 days of receiving the ITAT order. The High Court hears the appeal only if it is satisfied that the case involves a substantial question of law. It does not ordinarily reopen findings of fact.
The demand can be recovered unless it is stayed. A stay application is usually made to the Assessing Officer and then the Principal Commissioner. The CBDT guidance of 29 February 2016 refers to 20% of the disputed demand as a general reference. Each case is judged on its facts.
A notice under Section 148 is not appealed as such. It is answered during the Section 148A process, and the assessment that follows is appealed to the CIT(A). A notice that is out of time or without valid sanction may be challenged by writ petition in the High Court.
Yes. A penalty order is appealable to the CIT(A) under Section 246A in its own Form 35, usually within 30 days, even if the appeal on the assessment is pending. Whether the penalty is sustainable often depends on how the satisfaction was recorded.
Many steps can be done remotely with a signed authority and scanned documents, and hearings are often held online. Verification of the appeal and the payment of fees must follow the rules, and a valid Indian PAN is needed. Share the notice and the dates early.
Sudip argues matters at the CIT(A), ITAT and Calcutta High Court himself. Where a special leave petition is required, it is filed through the chambers’ Supreme Court connection. Whether the Court will entertain it is for the Court to decide.