DRT Kolkata: How a Bank Recovery Case Moves Through the Debts Recovery Tribunal
The Debts Recovery Tribunal (DRT) decides recovery claims by banks and financial institutions, and hears SARFAESI challenges by borrowers and guarantors. This page explains, step by step, how a case proceeds from the Original Application to an appeal before the DRAT.
What the DRT does, and why banks and borrowers end up there
The Debts Recovery Tribunal is a special forum created under the Recovery of Debts and Bankruptcy Act, 1993 (the RDB Act) so that banks and financial institutions can recover dues without the delay of an ordinary civil suit. Under Section 17, it decides applications for recovery of debts due to banks and financial institutions, and Section 18 bars civil courts from entertaining such claims. The Tribunal also hears applications under Section 17 of the SARFAESI Act, 2002 by borrowers and guarantors who challenge measures taken by a secured creditor. The official tribunal listings and notices are at drt.gov.in.
In Kolkata, matters are filed before the DRT benches here, and an aggrieved party may then go to the Debts Recovery Appellate Tribunal (DRAT). A recovery application by a bank is generally maintainable where the debt is ₹20 lakh or more, subject to the notification in force, which should always be verified. Borrowers, guarantors, mortgagors and even purchasers at auction sometimes find themselves before the Tribunal without knowing the sequence of steps. Our DRT lawyer in Kolkata page explains how we assist parties on either side of such a case.
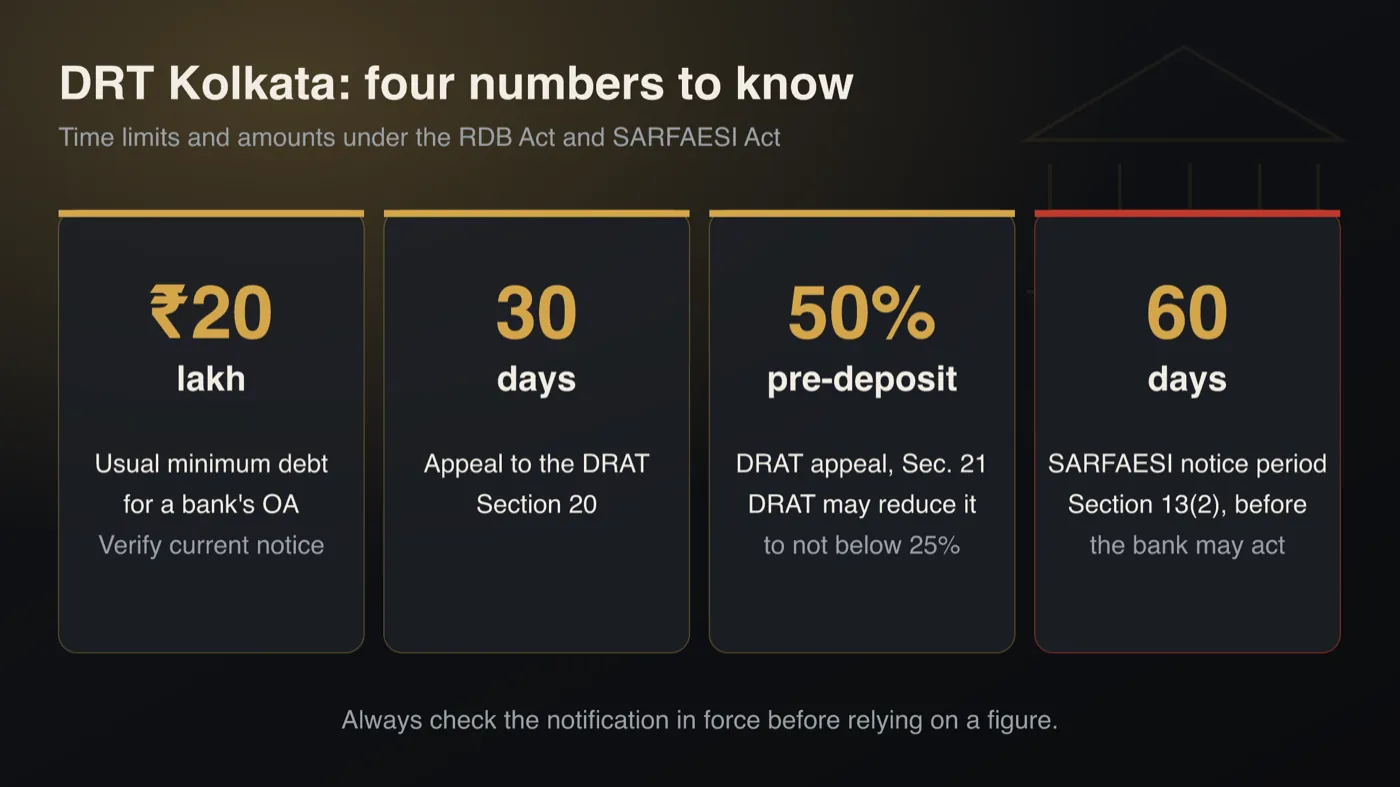
Four dates borrowers should know
Missing a date can cost the borrower a remedy, so these periods are worth marking early.
Short explainers from Adv. Sudip Patra
More short explainers on our YouTube channel: Patra’s Law Chambers on YouTube ↗
What paper or notice have you received from the bank or the tribunal?
Pick the closest match to see the forum and the usual next step. This is general information, not advice on your file. Please verify the details with an advocate who has read your papers.
Choose one of the options above.
How a bank case moves through the Debts Recovery Tribunal
This is the usual sequence in an Original Application by a bank. Actual timelines vary from bench to bench. See also our page on a DRT lawyer in Kolkata.
The bank or financial institution files an Original Application under Section 19 of the RDB Act. It must be for a debt of the minimum value notified by the Central Government, currently Rs 20 lakh. Section 17 decides which DRT has territorial jurisdiction.
The tribunal examines the application and issues summons to the defendant, who may be the borrower, the guarantors and the mortgagors. The defendant appears on the date given and may ask for the documents the bank relies on.
The defendant files a written statement that answers the bank’s claim. The RDB Act also allows a set-off or a counter-claim in appropriate cases. Late filing needs the tribunal’s permission, so the date on the summons matters.
The bank may ask for attachment or restraint on the sale of assets under Section 19(13) of the RDB Act. The defendant can oppose it or ask the DRT to vacate or modify it. Orders on such applications can also be taken further, so a Calcutta High Court advocate may be needed at a later stage.
Parties produce documents and arguments are heard. The Presiding Officer then passes a final order that determines the amount due. Where the bank succeeds, the DRT issues a recovery certificate.
An appeal lies to the DRAT under Section 20, within 30 days of receiving the order. Section 21 requires a pre-deposit, usually 50% of the amount, before the appeal is heard. If the debtor is a company in insolvency, the NCLT route may also be relevant.
Myths and facts about the DRT, tap a card
No. It is a special tribunal under the RDB Act and it decides recovery claims of banks and financial institutions. The Code of Civil Procedure does not apply in full, and the tribunal follows its own rules and procedure.
Not safely. If you do not answer the claim, the bank’s case may be decided on its documents alone. File the written statement within the time allowed.
Generally no. Section 21 of the RDB Act requires a pre-deposit of 50% of the debt determined by the DRT. The DRAT may reduce it to not less than 25% for reasons recorded in writing.
The stages of a bank case before the DRT
Original Application (OA) and summons
The bank files an OA with the statement of account, loan documents and details of securities. The Tribunal issues summons to the defendants, who are the borrower, guarantors and mortgagors. Receiving a summons is the point at which a borrower should take legal advice and collect all loan papers.
Written statement, set-off and counterclaim
The defendant files a written statement within the time the Act allows, which is short and extended only to a limited degree. A defendant may also claim set-off or raise a counterclaim. Missing the time can seriously weaken the defence, so the date of service of summons should be noted carefully.
Interim relief and attachment
Either side may apply for interim orders. A bank may seek attachment of property or a direction against disposal of assets, while a borrower may seek protection against coercive steps. The Tribunal weighs the documents on record before passing any order, and these orders are open to challenge in appeal.
Final order and appeal to the DRAT
After hearing, the Presiding Officer passes a final order. An appeal lies to the DRAT within 30 days under Section 20. Under Section 21, a borrower who appeals against a recovery order must pre-deposit 50% of the debt amount, which the DRAT may reduce, for recorded reasons, to not less than 25%.
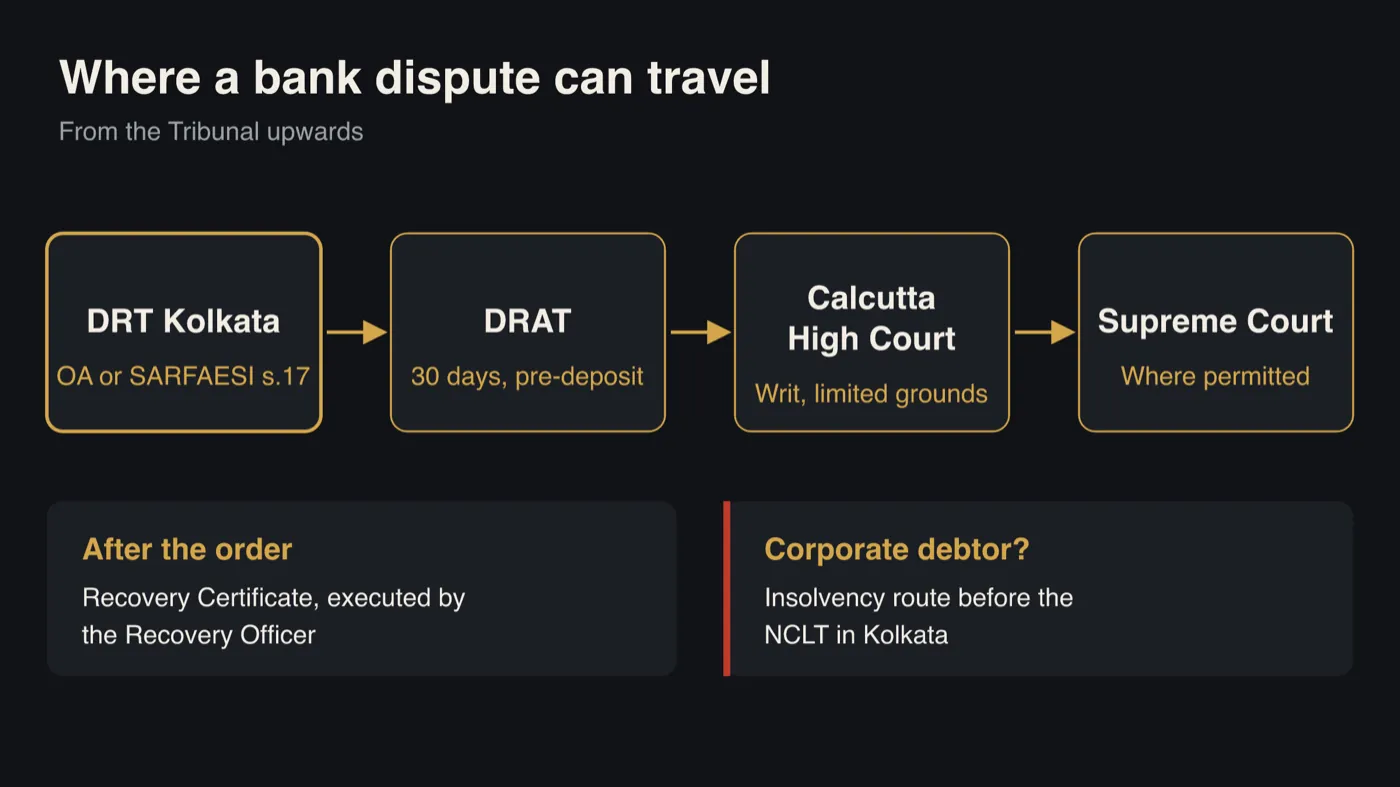
What happens after the order, and where else a dispute can travel
- Recovery Certificate issued by the Tribunal and executed by the Recovery Officer (Sections 19(22) and 25 to 28)
- SARFAESI challenge by borrowers under Section 17 of the SARFAESI Act, 2002, after a Section 13(2) notice
- Appeal against a Section 17 SARFAESI order to the DRAT, with a pre-deposit under Section 18 of the SARFAESI Act
- Writ jurisdiction of the Calcutta High Court over DRAT orders, on limited grounds
- Insolvency route before the NCLT in Kolkata where a corporate debtor is involved
- Further challenge before the Supreme Court, where permitted
DRT and DRAT: the judgments that shape a bank recovery case
These Supreme Court decisions settle who may be sued before the Debts Recovery Tribunal, when the High Court will step in, and what a borrower must deposit before appealing to the DRAT.
2002
The RDB Act and DRTs are constitutionally valid
The Delhi High Court had struck down the Recovery of Debts Act, 1993 as eroding judicial independence. The Supreme Court reversed that. It held the Act valid and said specialised tribunals do not undermine the judiciary. It also noted that the amendments allowing counter-claims and set-off cured the earlier gaps, and that DRAT orders remain subject to High Court review under Articles 226 and 227.
2006
A borrower's own civil suit stays in civil court
The bar on civil courts in the RDB Act covers recovery claims by banks. It does not cover independent suits by borrowers. A borrower’s suit for damages against the bank cannot be moved to the DRT without the borrower’s consent, even when the bank’s recovery case is already pending there. The borrower may still choose to raise the claim as a counter-claim before the Tribunal.
2010
Use the tribunal first, not a writ
Insisting on an alternative remedy is a matter of the court’s discretion. Even so, the Supreme Court said a High Court should not normally hear Article 226 petitions or grant interim stays where the DRT Act and the SARFAESI Act already give an effective remedy. The Court was seriously concerned that High Courts kept bypassing these tribunals in recovery matters.
2011
Pre-deposit for a SARFAESI appeal cannot be waived
This appeal came from Kolkata. The Supreme Court upheld the Calcutta High Court and held that the DRAT has no power to exempt a borrower from the pre-deposit required by Section 18 of the SARFAESI Act. The deposit is a condition of the right of appeal. The Appellate Tribunal may reduce it to 25 per cent for recorded reasons, but it cannot waive it altogether.
2018
No writ against SARFAESI steps where appeal lies
The Supreme Court set aside a High Court interim order that had stayed SARFAESI action after the borrower deposited a small sum. The borrower’s route is an application to the DRT under Section 17 and then an appeal to the DRAT under Section 18. The Court warned that ex parte interim orders in financial matters can cause serious harm.
2021
Section 21 pre-deposit before the DRAT is mandatory
An appeal against a DRT order under the RDB Act cannot be heard until the pre-deposit under Section 21 is made. The DRAT may reduce it, for recorded reasons, to not less than 25 per cent of the debt the DRT determined, but cannot waive it. The Supreme Court set aside a High Court order that had let the appeal go ahead without any deposit.
How a bank case proceeds before the DRT in Kolkata
Bank files an Original Application
Under Section 19 of the Recovery of Debts and Bankruptcy Act, 1993, a bank or financial institution files an Original Application (OA) for recovery of a debt of Rs. 20 lakh or more. It files it before the DRT with territorial jurisdiction, usually where the borrower lives or carries on business, or where the cause of action arose.
Summons and written statement
The Tribunal issues summons with the OA and its documents. The borrower and guarantors must file a written statement within 30 days of service, and the Tribunal may allow up to 15 more days. Any claim for set-off or counter-claim against the bank goes in the same written statement under Section 19.
Interim orders
At any stage the bank may ask for interim relief under Section 19. This can include an order stopping the borrower from transferring or encumbering assets, attachment before judgment, or appointment of a receiver. The borrower can oppose these orders and ask for them to be varied or vacated on the facts.
Hearing, final order and recovery certificate
After evidence, usually by affidavit, and arguments, the Presiding Officer passes a final order. If the claim succeeds, the DRT issues a recovery certificate for the amount due with interest under Section 19(22). The Act asks the Tribunal to try to decide the OA within 180 days, though in practice timelines vary.
Execution by the Recovery Officer
The Recovery Officer enforces the certificate under Section 25. Methods include attaching and selling movable or immovable property, appointing a receiver and, in limited cases, arrest. Objections to the Recovery Officer’s orders go back to the Presiding Officer of the DRT under Section 30.
Appeal to the DRAT with pre-deposit
A party aggrieved by the DRT’s final order may appeal to the Debts Recovery Appellate Tribunal (DRAT) under Section 20 within 45 days. A borrower’s appeal is heard only after depositing 50 per cent of the debt the DRT determined, which the DRAT may reduce to 25 per cent under Section 21. See our DRT and banking matters page.
How much must be deposited before a DRAT appeal is heard
The deposit is a condition of the appeal. The DRAT may reduce it for recorded reasons, but it cannot waive it.
Pre-deposit for a borrower's appeal to the DRAT under Section 21 of the Recovery of Debts and Bankruptcy Act, 1993 (on the debt determined by the DRT)
Mistakes borrowers and guarantors make at the DRT
Ignoring the DRT summons If no written statement is filed in time, the Tribunal may decide the OA ex parte and issue a recovery certificate. Setting that order aside later is harder than defending the case at the start.
Leaving the counter-claim out Any set-off or counter-claim against the bank should be raised in the written statement under Section 19. If it is not raised in time, it may be lost in that proceeding, so check whether a separate civil suit is the better route.
Going straight to the High Court After Satyawati Tondon and Mathew K.C., a writ petition against DRT or SARFAESI action is usually turned away when the statutory remedy before the DRT or DRAT is available. Writs are kept for narrow exceptions, such as action without jurisdiction or a breach of natural justice.
Assuming the DRAT will waive the deposit The pre-deposit under Section 21 of the RDB Act, or Section 18 of the SARFAESI Act, cannot be fully waived. At most it can be reduced to 25 per cent, so plan the funds and the 45-day limitation together.
Facing a bank notice, summons or recovery certificate?
Whether you are a borrower, guarantor, mortgagor or a lender, the first step is to read the loan documents, the notices received and the dates that matter. We can review those papers with you and explain the forum, the time limits and the options open under the RDB Act and the SARFAESI Act. Each matter turns on its own facts, and no result can be promised. Our related page on cheque bounce cases in Kolkata may also help if your dispute has a cheque-dishonour angle.
Book a ConsultationEstablished by a distinguished alumnus of IIT Kharagpur, Patra’s Law Chambers stands as a beacon of legal expertise in Kolkata & Delhi. Know more →
Kolkata Office
NICCO House, 6th Floor, 2 Hare Street
Kolkata-700001 (Near Calcutta High Court)
Delhi Office
4455/5, First Floor, Gali Shahid Bhagat Singh
Main Bazar Road, Paharganj, New Delhi-110055
Contact
[email protected]
+91 890 222 4444 / +91 7003 715 325
Original Application and Securitisation Application
Both are heard in the DRT, but one is filed by the bank and the other by the borrower.
Frequently asked questions about the DRT and bank recovery cases
The DRT hears applications by banks and financial institutions to recover debts under the Recovery of Debts and Bankruptcy Act, 1993. It also hears challenges by borrowers to SARFAESI measures such as possession or sale of secured assets, under Section 17 of the SARFAESI Act.
It is the bank’s case for recovery, filed under Section 19 of the RDB Act. It is for debts above the value notified by the Central Government, currently Rs 20 lakh. It sets out the loan, the default, the amount due and the securities.
The usual time is 30 days from service of summons on the defendant. The tribunal may permit later filing in suitable cases. Do not rely on an extension, and check the date written on your summons.
A borrower or any person aggrieved files a Securitisation Application before the DRT under Section 17 of the SARFAESI Act. The period is 45 days from the date the measure was taken. Please check your dates and papers promptly.
The DRT can grant interim relief, and this depends on the facts and the documents. It may order the bank not to proceed, or it may impose conditions such as a deposit. Whether relief is granted is for the tribunal to decide in each case.
An appeal against a DRT order lies under Section 20 of the RDB Act within 30 days of the order being received. The DRAT may allow a delay only if it is satisfied that there was sufficient cause for it.
Yes, usually. Under Section 21 of the RDB Act the appellant must deposit 50% of the debt determined by the DRT. The DRAT may reduce it to not less than 25% after recording reasons. The SARFAESI Act has a similar rule in Section 18.
The RDB Act does not give a further appeal. The High Court can be approached under Articles 226 and 227 of the Constitution, but its power is limited. This is considered only after the DRAT order and the reasons are examined.